Not every profit comes from selling goods or providing services. Sometimes, a business earns a profit from a capital transaction. Such profits may give rise to a capital reserve.
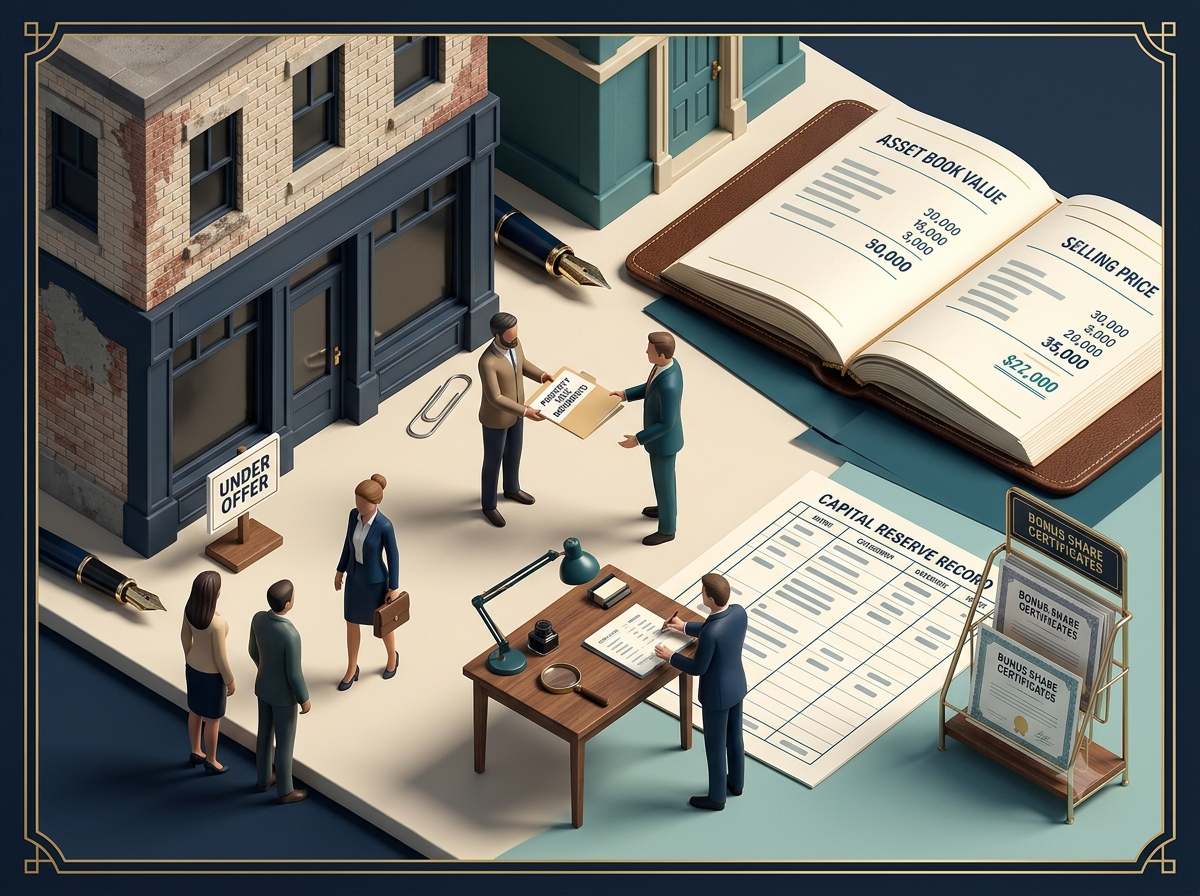
Imagine a company selling an old building for more than its book value. The profit from that sale may be a capital profit, subject to the applicable accounting rules.
6. State the Purposes for Which Capital Reserves Can Be Utilised
A capital reserve is created out of capital profits or other qualifying capital sources rather than ordinary revenue profits.
Capital reserves may be used for permitted purposes, such as:
1. Writing off capital losses: A capital reserve may be used to write off capital losses where permitted.
2. Issuing bonus shares: Certain capital reserves may be used to issue bonus shares, subject to the applicable rules.
3. Other permitted purposes: Their use depends on the nature of the reserve and the relevant accounting and legal requirements.
For example, a company earns a qualifying capital profit and transfers it to a capital reserve. It may later use an eligible reserve to issue bonus shares if the applicable conditions are satisfied.
A capital reserve is not a general-purpose fund that can automatically be used for any business expense or distributed freely as dividends.
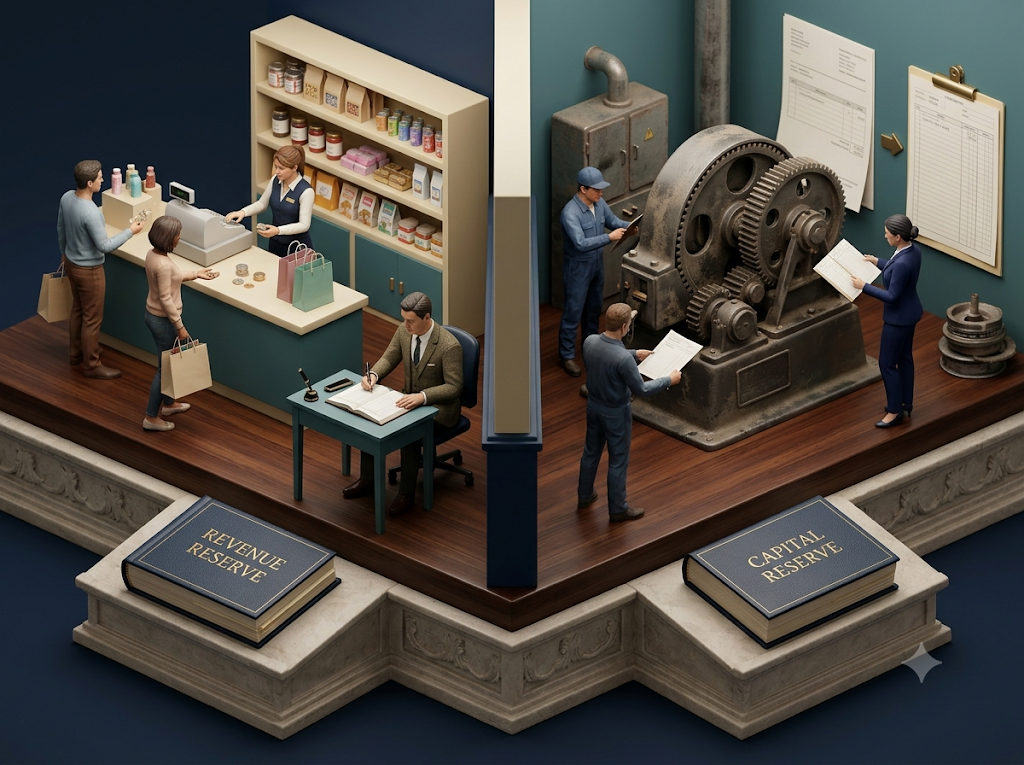
Capital Reserve vs Revenue Reserve
A capital reserve arises from capital profits or other qualifying capital sources.
A revenue reserve is created from revenue profits earned through the normal activities of the business.
For example, profit from ordinary sales may contribute to a revenue reserve, whereas a qualifying capital profit may contribute to a capital reserve.
Exam-ready memory line: Capital reserves arise from capital profits and may be used only for purposes permitted by the applicable rules.