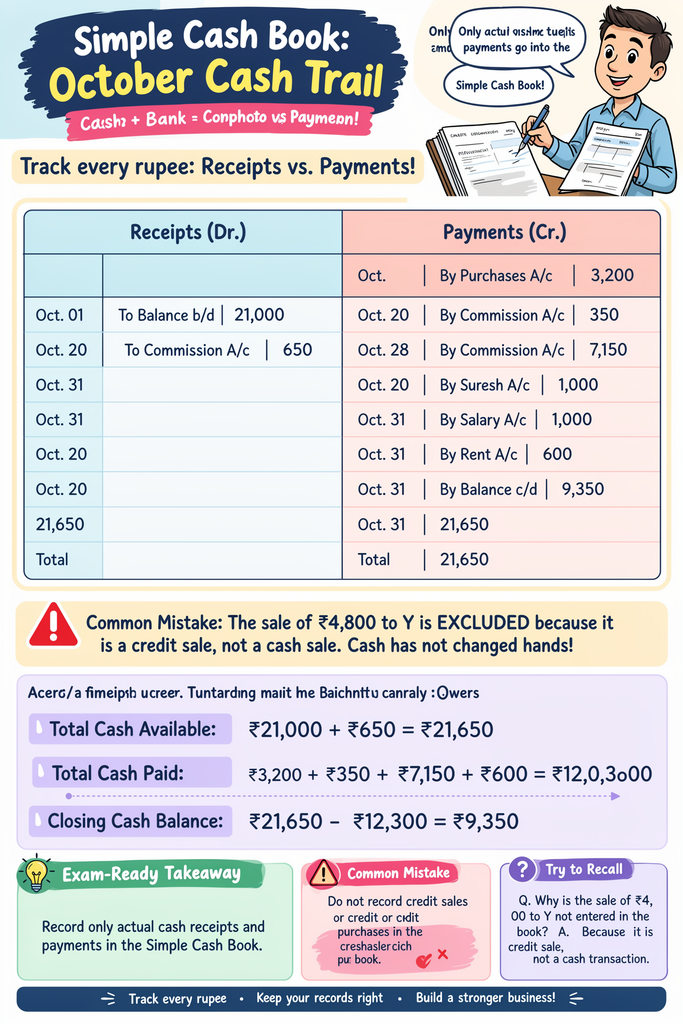
Srimath begins October with ₹21,000 in cash. During the month, goods are purchased, commission is received, payments are made, and office expenses are settled. By 31 October, the task is to determine how much cash remains.
The key is to follow every cash movement carefully. Cash received is recorded on the debit side; cash paid is recorded on the credit side.
Step 1: Examine the transactions
Some entries need careful attention:
- Opening cash balance: ₹21,000, recorded on the debit side.
- Goods purchased for cash: ₹3,200, recorded on the credit side.
- Goods sold to Y: ₹4,800 is described as a credit sale because the wording says “sold goods to Y.” Unless the question confirms that cash was received immediately, this is not entered in a Simple Cash Book.
- Commission received: ₹650, recorded on the debit side.
- Commission paid: ₹350, recorded on the credit side.
- Payment to Suresh: ₹7,150, recorded on the credit side, assuming it was paid in cash.
- Salary and office rent: ₹1,000 and ₹600, respectively, recorded on the credit side.
Step 2: Prepare Srimath’s Simple Cash Book
For October
| Date | Particulars — Debit side (Receipts) | Amount (₹) |
|---|---|---|
| Oct. 01 | To Balance b/d | 21,000 |
| Oct. 20 | To Commission A/c | 650 |
| Total receipts | 21,650 |
| Date | Particulars — Credit side (Payments) | Amount (₹) |
|---|---|---|
| Oct. 08 | By Purchases A/c | 3,200 |
| Oct. 20 | By Commission A/c | 350 |
| Oct. 28 | By Suresh A/c | 7,150 |
| Oct. 31 | By Salary A/c | 1,000 |
| Oct. 31 | By Rent A/c | 600 |
| Oct. 31 | By Balance c/d | 9,350 |
| Total payments | 21,650 |
Note: The sale of ₹4,800 to Y is excluded because the question does not state that it was a cash sale. A credit sale is recorded in the appropriate account, not in the Simple Cash Book. If the original question intended a cash sale, the closing balance would instead be ₹14,150.
Step 3: Calculate the closing balance
Total cash available, including commission received:
\[ ₹21,000+₹650=₹21,650 \]
Total cash payments:
\[ \begin{aligned} ₹3,200+₹350+₹7,150+₹1,000+₹600 =₹12,300 \end{aligned} \]
Therefore,
\[ \begin{aligned} \text{Closing cash balance} &=₹21,650-₹12,300\\ &=\boxed{₹9,350} \end{aligned} \]
The final takeaway
On the stated assumption that the sale to Y was a credit sale, Srimath’s closing cash balance on 31 October is ₹9,350.
Exam memory cue: Record only actual cash receipts and payments in the Simple Cash Book. A transaction involving a customer does not automatically mean cash has changed hands.