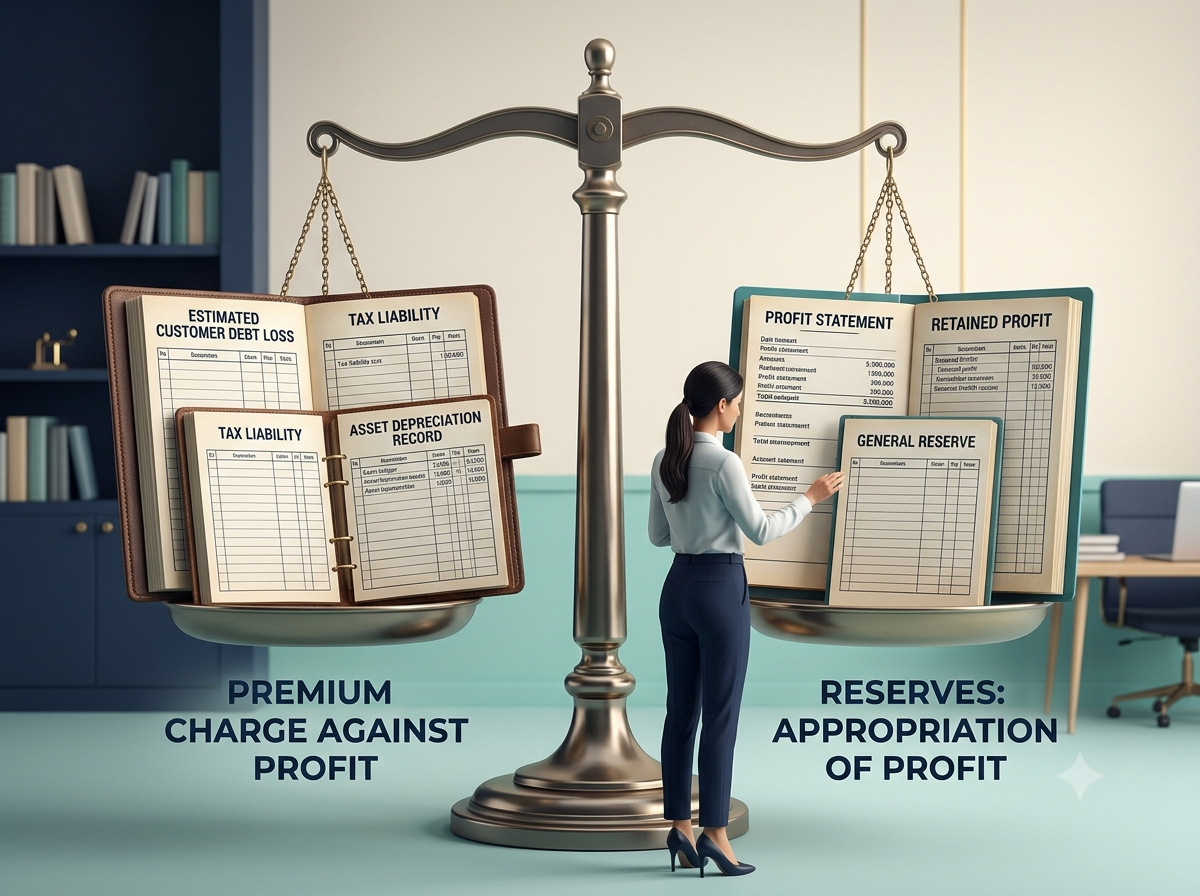
Businesses need different financial arrangements for different purposes. Some reserves come from normal business profits, some are created for a specific objective, and a sinking fund helps prepare for a future payment or asset replacement.
8. Describe Briefly the Following
i. Secret Reserves
A secret reserve is a reserve that is not clearly disclosed in the balance sheet. In traditional accounting explanations, it may arise when assets are undervalued, or liabilities are overvalued.
For example, if a business reports an asset at a value lower than its properly determined value, part of its financial strength may remain hidden.
This is a traditional textbook concept, not permission to manipulate financial statements.
ii. Revenue Reserves
Revenue reserves are created out of revenue profits earned through the normal activities of a business.
For example, a shop earns profits by selling goods and retains part of those profits instead of distributing the entire amount to its owner. The retained amount may contribute to a revenue reserve.
Revenue reserves help strengthen the financial position of the business and may be general or specific, depending on their purpose.
iii. Specific Reserves
A specific reserve is created for a particular purpose.
Examples include a plant replacement reserve for replacing machinery or a dividend equalisation reserve intended to help maintain a stable dividend.
The reserve is intended for its stated purpose, subject to the applicable rules.
iv. Sinking Fund
A sinking fund is a fund built up through regular contributions that are invested systematically to meet a future requirement, such as repaying a long-term debt or replacing an asset.
For example, a company expects to repay a large debt several years later. It accumulates and invests amounts over time so that funds can be available when the payment becomes due.
The accounting treatment depends on the purpose of the fund and the applicable rules.
Quick Revision
- Secret reserve: A reserve not clearly disclosed in the balance sheet.
- Revenue reserve: A reserve created out of revenue profits.
- Specific reserve: A reserve created for a defined purpose.
- Sinking fund: A fund accumulated and invested for a future payment or asset replacement.
Exam-ready memory line: Revenue reserves arise from revenue profits, specific reserves serve defined purposes, secret reserves are not clearly disclosed, and sinking funds accumulate investments for future requirements.