
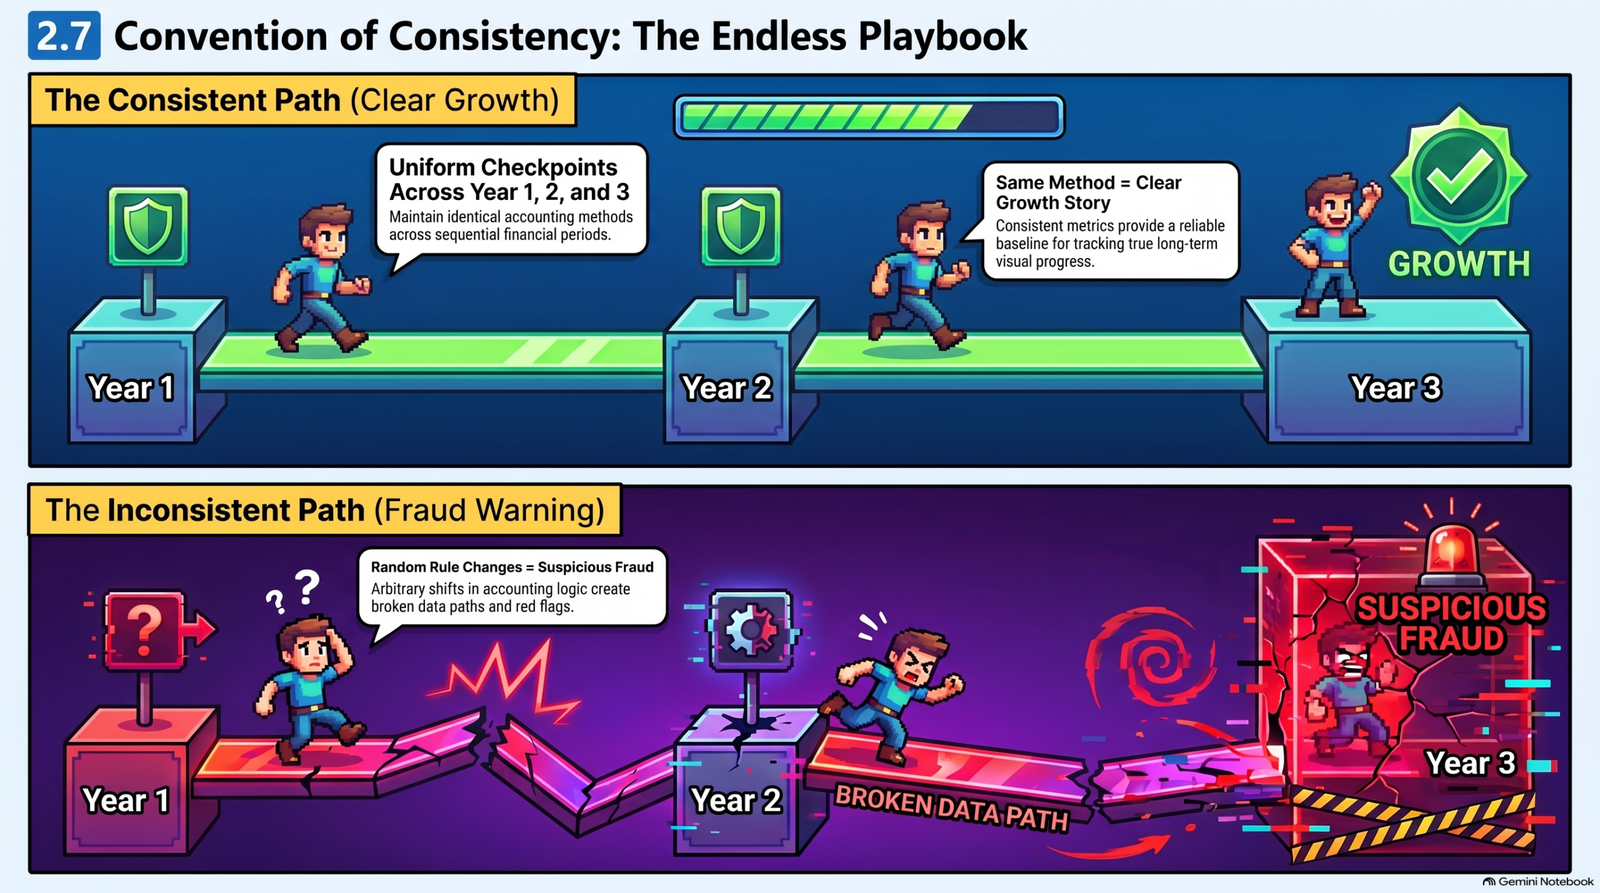
Imagine playing your favorite video game, and halfway through level three, the developers suddenly change the controls so that the jump button now makes your character freeze and dance. You’d be furious! You can’t beat your high score, track your progress, or figure out if you’re actually getting better if the rules keep shifting under your feet.
In the financial world, businesses face the exact same challenge. Welcome to the Convention of Consistency—the unwritten rule that keeps financial scorecards honest, steady, and crystal clear year after year.
What is the Convention of Consistency? 📏
Here is the core idea in plain human language: Once a business chooses a specific accounting method or policy, it must stick with it consistently across future accounting periods, rather than chopping and changing methods on a whim.
Accounting often gives you a few different legal ways to calculate things—like how you calculate the wear and tear of machinery or how you value your unsold stock in the warehouse.
The Convention of Consistency says: Pick your method, commit to it, and use it year after year.
Why is Consistency Your Superpower? 🤔
You might wonder: “If there are multiple ways to calculate things, why not use whichever one feels easiest this month?”
Because business is all about comparison.
- If an investor looks at a company’s profits for 2024 and compares them to 2025, they need to know that the increase (or decrease) is real business growth—not just the result of the accountant changing the math formulas behind the scenes!
- Consistency turns financial statements into an “apples-to-apples” comparison. It builds massive trust with banks, tax authorities, and investors because they know the playbook isn’t being rewritten every time profits dip.
(Note: Consistency doesn’t mean a business can never change a method. If a new law passes or a change genuinely gives a fairer, truer picture of the business, the change is allowed—but the business must publicly disclose that they changed it and why!)
Real-Life Scenario: The Magic Profit Trick 🪄📉
Picture two rival retail stores, Store A and Store B:
- Store A uses the exact same inventory valuation method every single year. Even when sales drop slightly, their numbers are honest, transparent, and trusted by their bank.
- Store B has a rough year. Instead of fixing their sales, the owner tells the accountant: “Hey, let’s switch our depreciation and inventory calculation methods this year so our expenses look smaller and our profits look huge!”
When the bank looks at Store B’s books, they get suspicious. By breaking consistency, Store B has made it impossible for anyone to tell if the business is actually healthy or just playing math tricks.
Concept Snapshot Table
| Feature | The Consistent Approach ✅ | The Inconsistent Trickery ❌ |
| Method Choice | Using the same accounting policy year after year. | Changing methods randomly whenever it suits the mood. |
| Comparability | Easy to track real growth over time. | Impossible to compare years; looks shady to outsiders. |
| Trust Level | High trust with investors, banks, and tax offices. | Low trust; triggers red flags during financial audits. |
To make sure this tradition is permanently locked into your brain: If a company suddenly shifts its inventory valuation method every year just to make its profits look artificially high to investors, which vital accounting convention are they breaking, and why does this destroy trust?