Imagine running a business and discovering that your bank account has a negative balance of ₹12,500.
You have used more money than you currently have in your account, and the bank has allowed you to borrow the difference under an overdraft facility.
Now imagine that your Cash Book shows an overdraft of ₹12,500, but your Pass Book shows a different amount.
How do you reconcile the two?
The answer lies in understanding how an overdraft works and how each transaction affects the balance.
1. What Is a Bank Overdraft?
A Bank Overdraft is a facility provided by a bank that allows a customer to withdraw more money than the available balance in their account, up to an agreed limit.
In simple words, the business temporarily borrows money from the bank.
An overdraft is represented by a credit balance in the bank column of the Cash Book and a debit balance in the Pass Book.
For example:
- Cash Book debit balance: ₹10,000 — favourable balance.
- Cash Book credit balance: ₹10,000 — overdraft.
Remember that a favourable balance means money is available in the account, whereas an overdraft means the business owes money to the bank.
2. The Golden Rule: Understand the Starting Balance
When preparing a BRS with an overdraft, first identify whether the question starts with the Cash Book or the Pass Book.
The safest method is to imagine a favourable bank balance as positive and an overdraft as negative.
This prevents confusion when adding and subtracting amounts.
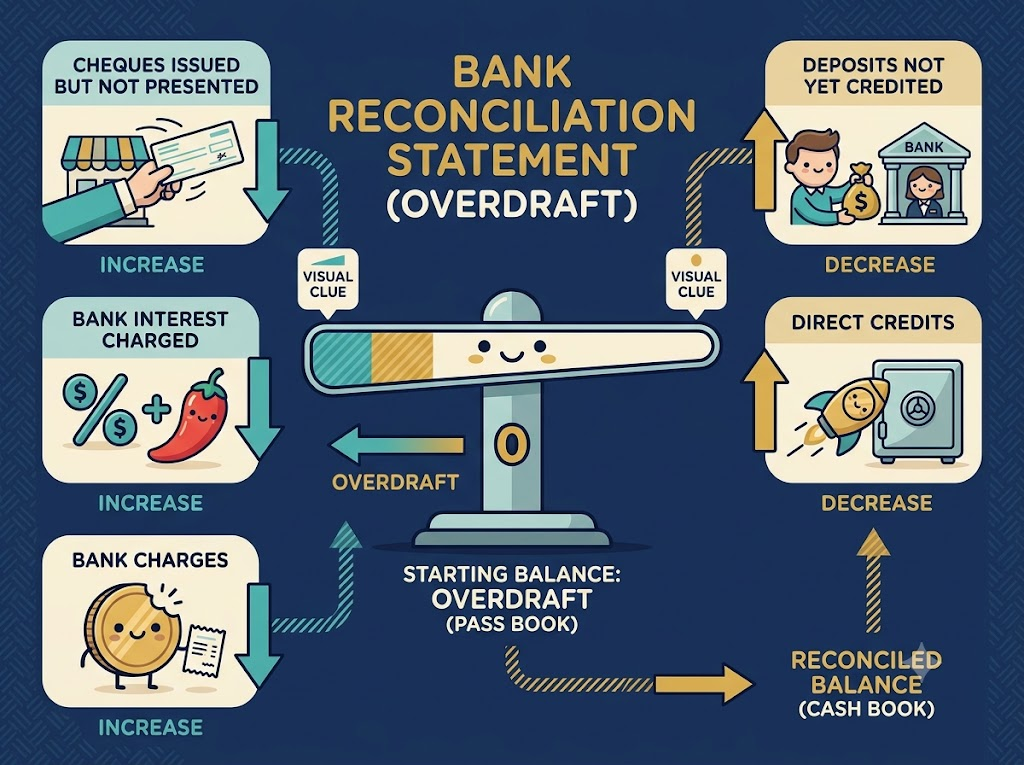
When starting with a Cash Book overdraft and finding the Pass Book overdraft:
| Transaction | Adjustment |
|---|---|
| Cheques issued but not presented | Add |
| Cheques deposited but not collected | Subtract |
| Bank charges not recorded in Cash Book | Subtract |
| Interest on overdraft not recorded in Cash Book | Subtract |
| Income credited by bank but not recorded in Cash Book | Add |
When starting with a Pass Book overdraft and finding the Cash Book overdraft, reverse these adjustments.
Let’s put this method into action.
3. Example One: Basic Bank Overdraft Reconciliation
Question:
From the following particulars, prepare a Bank Reconciliation Statement as on 31 March 2012:
- Overdraft as per Cash Book: ₹12,500.
- Cheques of ₹18,000 were issued but were not presented for payment.
- Cheques of ₹24,000 were paid into the bank but were not credited by 31 March 2012.
- Bank charges: ₹1,500.
Step 1: Start with the Cash Book Overdraft
Overdraft as per Cash Book = ₹12,500.
For calculation purposes, represent it as −₹12,500.
Step 2: Add Cheques Issued but Not Presented
The business issued cheques worth ₹18,000.
The Cash Book has already recorded these payments, but the bank has not deducted the amount because the cheques have not been presented.
Therefore, the Pass Book balance is higher than the Cash Book balance.
Add ₹18,000.
Step 3: Subtract Cheques Deposited but Not Credited
Cheques worth ₹24,000 were deposited, but the bank had not credited them.
The Cash Book has recorded the deposits, but the Pass Book has not.
Therefore, subtract ₹24,000.
Step 4: Subtract Bank Charges
The bank deducted ₹1,500 as charges.
The Cash Book has not recorded this deduction.
Therefore, subtract ₹1,500.
Final Bank Reconciliation Statement
Bank Reconciliation Statement as on 31 March 2012
| Particulars | Amount (₹) |
|---|---|
| Overdraft as per Cash Book | (12,500) |
| Add: Cheques issued but not presented | 18,000 |
| Less: Cheques deposited but not credited | (24,000) |
| Less: Bank charges | (1,500) |
| Overdraft as per Pass Book | (20,000) |
Calculation:
−₹12,500 + ₹18,000 − ₹24,000 − ₹1,500 = −₹20,000.
Therefore, the Pass Book shows an overdraft of ₹20,000.
Notice something important: the unpresented cheques reduce the overdraft, but the uncollected deposits and bank charges increase it.
4. Example Two: Overdraft with Interest and Investment Income
Now let’s introduce more transactions.
Question:
From the following particulars, ascertain the balance that would appear in the Bank Pass Book of Arun on 31 March 2012:
- Bank overdraft as per Cash Book: ₹60,200.
- Interest on overdraft for six months ending 31 March 2012: ₹10,000, entered in the Pass Book.
- Bank charges for the above period: ₹1,300, debited in the Pass Book.
- Cheques issued but not cashed before 31 March 2012: ₹10,620.
- Cheques paid into the bank but not cleared before 31 March 2012: ₹16,500.
- Interest on investment collected by the bank and credited in the Pass Book: ₹11,000.
Step 1: Start with the Cash Book Overdraft
Overdraft as per Cash Book = ₹60,200.
Represent it as −₹60,200.
Step 2: Subtract Interest on Overdraft
The bank has charged ₹10,000 as interest on the overdraft.
The bank has recorded the deduction, but the Cash Book has not.
Therefore, subtract ₹10,000.
Step 3: Subtract Bank Charges
The bank has also deducted ₹1,300 as bank charges.
Since these charges are missing from the Cash Book, subtract ₹1,300.
Step 4: Add Cheques Issued but Not Cashed
Cheques worth ₹10,620 were issued but had not yet been presented.
The Cash Book has already recorded the payments, but the bank has not deducted them.
Therefore, add ₹10,620.
Step 5: Subtract Cheques Deposited but Not Cleared
Cheques worth ₹16,500 were deposited but had not been cleared.
The Cash Book has recorded the deposits, but the bank has not credited the money.
Therefore, subtract ₹16,500.
Step 6: Add Interest on Investments
The bank collected ₹11,000 as interest on investments and credited the amount to the account.
The Cash Book has not recorded this income.
Therefore, add ₹11,000.
Final Bank Reconciliation Statement
Bank Reconciliation Statement as on 31 March 2012
| Particulars | Amount (₹) |
|---|---|
| Overdraft as per Cash Book | (60,200) |
| Add: Cheques issued but not cashed | 10,620 |
| Add: Interest on investments collected by bank | 11,000 |
| Less: Interest on overdraft | (10,000) |
| Less: Bank charges | (1,300) |
| Less: Cheques deposited but not cleared | (16,500) |
| Overdraft as per Pass Book | (66,380) |
Calculation:
−₹60,200 + ₹10,620 + ₹11,000 − ₹10,000 − ₹1,300 − ₹16,500 = −₹66,380.
Therefore, the Pass Book shows an overdraft of ₹66,380.
5. Example Three: Starting with Pass Book Overdraft
Until now, we started with the Cash Book overdraft and calculated the Pass Book balance.
But what if the question gives the Pass Book overdraft and asks us to find the Cash Book overdraft?
Don’t panic! We simply reverse the adjustments.
Question:
Prepare a Bank Reconciliation Statement as on 31 March 2012 from the following particulars:
- Balance as per Pass Book (overdrawn): ₹10,266.
- Cheques drawn on 31 March 2012 but not cleared until 2 April 2012: ₹120, ₹10,211, ₹981 and ₹1,128.
- Interest on bank overdraft not entered in the Cash Book: ₹1,510.
- Outstation cheques worth ₹21,000 lodged in the bank on 30 March 2012 but credited in April 2012.
- Chamber of Commerce subscription of ₹100 paid by the bank under a standing order on 31 March 2012 but not entered in the Cash Book.
- A Hundi of ₹2,500 due on 31 March 2012 was sent to the bank for collection on 29 March 2012 and entered in the Cash Book immediately, but the proceeds were not credited in the Pass Book until 2 April 2012.
Step 1: Start with the Pass Book Overdraft
Overdraft as per Pass Book = ₹10,266.
Represent it as −₹10,266.
Step 2: Adjust Cheques Drawn but Not Cleared
First, calculate their total:
₹120 + ₹10,211 + ₹981 + ₹1,128 = ₹12,440.
The Cash Book has already recorded these payments, but the bank has not deducted them.
Therefore, the Cash Book overdraft is higher.
Subtract ₹12,440.
Step 3: Add Interest on Bank Overdraft
The bank has charged ₹1,510 as interest.
The Pass Book has recorded the interest, but the Cash Book has not.
Therefore, when finding the Cash Book balance, add ₹1,510 back.
Step 4: Add Outstation Cheques Not Yet Credited
Cheques worth ₹21,000 were deposited on 30 March but credited by the bank in April.
The Cash Book has recorded the deposit, but the Pass Book has not.
Therefore, add ₹21,000.
Step 5: Add the Chamber of Commerce Subscription
The bank paid ₹100 under a standing order.
A standing order is an instruction given by a bank customer authorising the bank to make regular payments on their behalf.
The Pass Book has recorded this payment, but the Cash Book has not.
Therefore, add ₹100.
Step 6: Add the Hundi Sent for Collection
A Hundi worth ₹2,500 was sent to the bank for collection and entered in the Cash Book immediately.
However, the bank had not credited the amount by 31 March.
Therefore, the Cash Book balance is higher than the Pass Book balance.
Add ₹2,500.
Final Bank Reconciliation Statement
Bank Reconciliation Statement as on 31 March 2012
| Particulars | Amount (₹) |
|---|---|
| Overdraft as per Pass Book | (10,266) |
| Less: Cheques drawn but not cleared | (12,440) |
| Add: Interest on bank overdraft | 1,510 |
| Add: Outstation cheques not credited | 21,000 |
| Add: Chamber of Commerce subscription | 100 |
| Add: Hundi sent for collection but not credited | 2,500 |
| Balance as per Cash Book | 2,404 |
Calculation:
−₹10,266 − ₹12,440 + ₹1,510 + ₹21,000 + ₹100 + ₹2,500 = ₹2,404.
The final balance is ₹2,404 favourable, not an overdraft.
This is an important result: even though the starting Pass Book balance was overdrawn, the corrected Cash Book balance is favourable.
6. Example Four: Partial Cheque Presentation and Direct Bank Transactions
This final problem introduces several different adjustments in one question.
Question:
Prepare a Bank Reconciliation Statement from the following particulars:
On 31 December 2016, the Pass Book showed an overdraft of ₹750.
- Cheques amounting to ₹250 were issued, but only ₹200 had been presented for payment.
- Cheques amounting to ₹100 were deposited on 30 December, but only ₹75 were credited in the Pass Book.
- A cheque of ₹1, which had been debited to the bank account in the books, was omitted from being banked.
- The Pass Book showed a debit of ₹25 for interest.
- A payment of ₹30 made directly into the bank by a customer appeared in the Pass Book.
- The Pass Book showed a credit of ₹60 for interest on investments collected by the bank.
Step 1: Start with the Pass Book Overdraft
Overdraft as per Pass Book = ₹750.
Represent it as −₹750.
Step 2: Calculate Unpresented Cheques
Total cheques issued = ₹250.
Cheques presented = ₹200.
Unpresented cheques:
₹250 − ₹200 = ₹50.
The Cash Book has already recorded the full payment, but the bank has deducted only ₹200.
Therefore, subtract ₹50.
Step 3: Calculate Uncollected Cheques
Total cheques deposited = ₹100.
Cheques credited by bank = ₹75.
Uncollected cheques:
₹100 − ₹75 = ₹25.
The Cash Book has recorded the full deposit, but the bank has credited only ₹75.
Therefore, add ₹25.
Step 4: Adjust the Cheque Omitted from Banking
The question states that a cheque of ₹1 was debited to the bank account in the books but was not actually banked.
This means the Cash Book has recorded an increase in the bank balance that the Pass Book does not show.
Therefore, add ₹1.
Important: The supplied answer uses ₹10 instead of ₹1. Unless the original textbook question confirms that the intended figure is ₹10, we must use the stated amount of ₹1.
Step 5: Add Interest Debited by the Bank
The Pass Book shows an interest deduction of ₹25.
The Cash Book has not recorded this deduction.
Therefore, add ₹25 when moving from Pass Book to Cash Book.
Step 6: Subtract the Direct Customer Payment
A customer directly deposited ₹30 into the bank.
The Pass Book recorded the amount, but the Cash Book did not.
Therefore, subtract ₹30.
Step 7: Subtract Interest on Investments
The bank collected ₹60 as interest on investments.
The Pass Book recorded the income, but the Cash Book did not.
Therefore, subtract ₹60.
Final Bank Reconciliation Statement
Bank Reconciliation Statement as on 31 December 2016
| Particulars | Amount (₹) |
|---|---|
| Overdraft as per Pass Book | (750) |
| Less: Unpresented cheques | (50) |
| Add: Cheques deposited but not credited | 25 |
| Add: Cheque omitted from banking | 1 |
| Add: Interest debited by bank | 25 |
| Less: Direct payment by customer | (30) |
| Less: Interest on investments collected by bank | (60) |
| Overdraft as per Cash Book | (839) |
Calculation:
−₹750 − ₹50 + ₹25 + ₹1 + ₹25 − ₹30 − ₹60 = −₹839.
Therefore, using the figure ₹1 exactly as supplied, the Cash Book shows an overdraft of ₹839.
If the original question actually says ₹10, the answer becomes an overdraft of ₹830.
7. The Overdraft Rules: Your Quick Reference
Here is the important comparison when preparing a BRS.
| Transaction | Starting with Cash Book overdraft | Starting with Pass Book overdraft |
|---|---|---|
| Cheques issued but not presented | Add | Subtract |
| Cheques deposited but not collected | Subtract | Add |
| Bank charges not recorded in Cash Book | Subtract | Add |
| Interest on overdraft not recorded in Cash Book | Subtract | Add |
| Income credited by bank but not recorded in Cash Book | Add | Subtract |
| Expenses paid by bank but not recorded in Cash Book | Subtract | Add |
Remember: these are adjustments for finding the opposite book’s balance. The direction changes when the starting point changes.
Final Takeaway
A bank overdraft is simply a negative bank balance. The most important skill in overdraft reconciliation is identifying which book has already recorded a transaction and which book has not.
Exam-ready memory line: When preparing a Bank Reconciliation Statement, always identify the starting balance first. Then adjust each transaction according to whether it increases or decreases the balance being calculated.