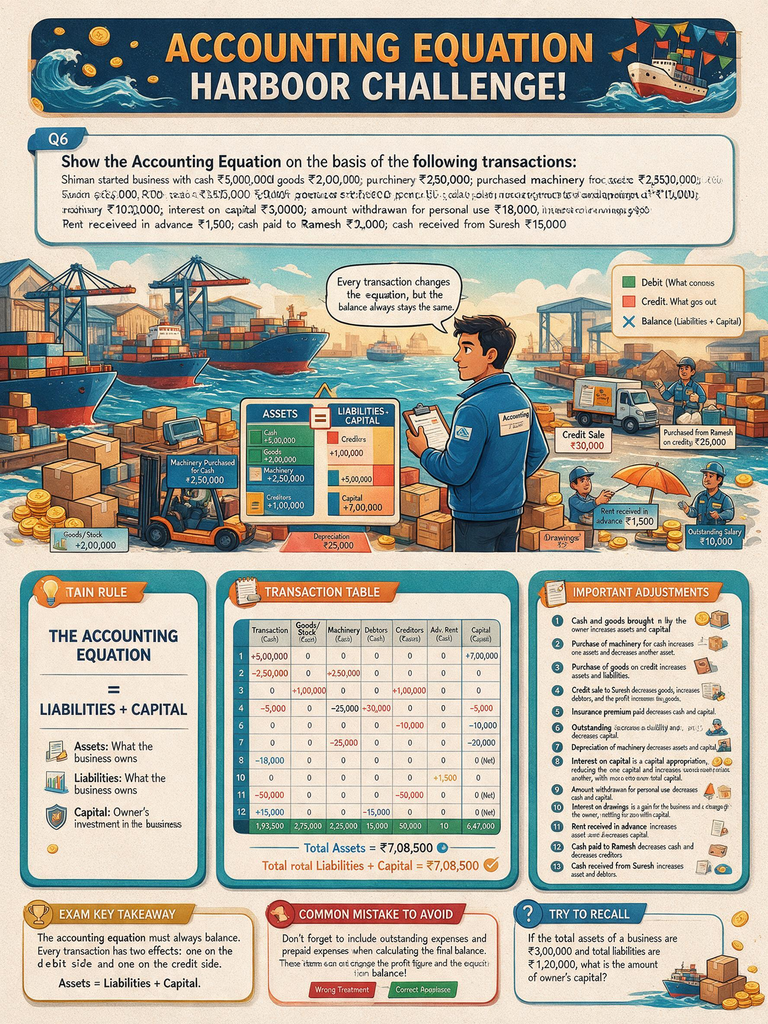
Imagine steering a massive cargo ship through a bustling international harbor. You aren’t just managing a single cash drawer anymore—you are tracking inventory, settling debts with suppliers, paying workers, handling asset wear-and-tear, and even collecting advance rents!
Running a complex trading enterprise requires recording these multifaceted events while keeping the financial scales in absolute, unshakeable harmony. Let’s break down Shivam’s massive transaction marathon step-by-step so you can master advanced accounting equations with total confidence and zero stress! 🚀
Step-by-Step Transaction Odyssey 🗺️
1. The Grand Launch 💼💵📦
- The Move: Shivam started business with cash of ₹5,00,000 and goods worth ₹2,00,000.
- Simple Solution Step: Initial capital includes both cash and inventory assets, matched entirely by owner’s equity.
- Equation Impact:$$\text{Assets (Cash } +5,00,000 \text{ \& Goods } +2,00,000) = \text{Liabilities } (0) + \text{Capital } (+7,00,000)$$
2. Upgrading the Gear ⚙️🛒
- The Move: Purchased machinery for cash of ₹2,50,000.
- Simple Solution Step: Liquid cash turns into solid fixed assets internally. Total assets stay balanced.
- Equation Impact:$$\text{Assets (Cash } -2,50,000 \text{ \& Machinery } +2,50,000) = \text{Liabilities } (0) + \text{Capital } (0)$$
3. Stocking Up on Trust 🤝📦
- The Move: Purchased goods from Ramesh on credit for ₹1,00,000.
- Simple Solution Step: Inventory increases, and a supplier creditor liability is born.
- Equation Impact:$$\text{Assets (Goods } +1,00,000) = \text{Liabilities (Creditors } +1,00,000) + \text{Capital } (0)$$
4. The Smart Sale Flip 📈🏷️
- The Move: Sold goods to Suresh costing ₹25,000 for ₹30,000 (Credit Sale).
- Simple Solution Step: Goods drop by cost, a debtor is created for the selling price, and the ₹5,000 profit boosts capital.
- Equation Impact:$$\text{Assets (Goods } -25,000 \text{ \& Debtors } +30,000) = \text{Liabilities } (0) + \text{Capital (Profit } +5,000)$$
5. Keeping the Lights On 💡💸
- The Move: Paid insurance premium of ₹5,000.
- Simple Solution Step: Outflow of cash reduces cash assets and cuts into capital as an operating expense.
- Equation Impact:$$\text{Assets (Cash } -5,000) = \text{Liabilities } (0) + \text{Capital } (-5,000)$$
6. The Shadow Bill ⏳👷♂️
- The Move: Salary outstanding of ₹10,000.
- Simple Solution Step: Creates an unpaid expense liability while reducing capital because the service was consumed.
- Equation Impact:$$\text{Assets } (0) = \text{Liabilities (Outstanding Salary } +10,000) + \text{Capital } (-10,000)$$
7. The Silent Wear and Tear 📉⚙️
- The Move: Depreciation of machinery worth ₹25,000.
- Simple Solution Step: Machinery loses value over time, acting as a non-cash expense that reduces both the asset and capital.
- Equation Impact:$$\text{Assets (Machinery } -25,000) = \text{Liabilities } (0) + \text{Capital } (-25,000)$$
8. Rewarding the Investor 💎🔄
- The Move: Interest on capital allowed at ₹3,000.
- Simple Solution Step: Acts as a business expense (reducing capital) and an owner addition (increasing capital), resulting in a net-zero impact on total equity components.
- Equation Impact:$$\text{Assets } (0) = \text{Liabilities } (0) + \text{Capital (Expense } -3,000 \text{ \& Addition } +3,000)$$
9. Personal Pocket Dip 🛍️🕵️♂️
- The Move: Amount withdrawn for personal use (Drawings) of ₹18,000.
- Simple Solution Step: Cash leaves the business register for personal needs, reducing cash assets and pulling down capital.
- Equation Impact:$$\text{Assets (Cash } -18,000) = \text{Liabilities } (0) + \text{Capital (Drawings } -18,000)$$
10. The Owner’s Return Interest 📝🔄
- The Move: Interest on drawings charged at ₹900.
- Simple Solution Step: Income for the business and a charge to the owner, balancing out within the capital structure.
- Equation Impact:$$\text{Assets } (0) = \text{Liabilities } (0) + \text{Capital (Income } +900 \text{ \& Charge } -900)$$
11. Advance Cash Blessing 📥💵
- The Move: Rent received in advance of ₹1,500.
- Simple Solution Step: Cash increases, but because the service isn’t delivered yet, it creates an unearned income liability.
- Equation Impact:$$\text{Assets (Cash } +1,500) = \text{Liabilities (Advance Rent } +1,500) + \text{Capital } (0)$$
12. Settling the Supplier 🤝💸
- The Move: Cash paid to Ramesh ₹50,000.
- Simple Solution Step: Cash decreases and creditor liabilities drop by the same amount.
- Equation Impact:$$\text{Assets (Cash } -50,000) = \text{Liabilities (Creditors } -50,000) + \text{Capital } (0)$$
13. Collecting from the Customer 🏃♂️💵
- The Move: Cash received from Suresh ₹15,000.
- Simple Solution Step: One asset (Debtors) turns into another liquid asset (Cash). Total assets remain balanced internally.
- Equation Impact:$$\text{Assets (Cash } +15,000 \text{ \& Debtors } -15,000) = \text{Liabilities } (0) + \text{Capital } (0)$$
Master Transaction Tracking Table 📊
| Transaction Step | Cash (🪙) | Goods/Stock (📦) | Machinery (⚙️) | Debtors (🏃♂️) | Creditors (📜) | O/S Salary (⏳) | Adv. Rent (📥) | Capital (💎) |
| Initial Start | $+5,00,000$ | $+2,00,000$ | $0$ | $0$ | $0$ | $0$ | $0$ | $+7,00,000$ |
| 1. Buy Machinery | $-2,50,000$ | $0$ | $+2,50,000$ | $0$ | $0$ | $0$ | $0$ | $0$ |
| 2. Buy Goods on Credit | $0$ | $+1,00,000$ | $0$ | $0$ | $+1,00,000$ | $0$ | $0$ | $0$ |
| 3. Credit Sale to Suresh | $0$ | $-25,000$ | $0$ | $+30,000$ | $0$ | $0$ | $0$ | $+5,000$ |
| 4. Paid Insurance | $-5,000$ | $0$ | $0$ | $0$ | $0$ | $0$ | $0$ | $-5,000$ |
| 5. Salary Outstanding | $0$ | $0$ | $0$ | $0$ | $0$ | $+10,000$ | $0$ | $-10,000$ |
| 6. Depreciation | $0$ | $0$ | $-25,000$ | $0$ | $0$ | $0$ | $0$ | $-25,000$ |
| 7. Interest on Capital | $0$ | $0$ | $0$ | $0$ | $0$ | $0$ | $0$ | $0$ (Net) |
| 8. Personal Drawings | $-18,000$ | $0$ | $0$ | $0$ | $0$ | $0$ | $0$ | $-18,000$ |
| 9. Interest on Drawings | $0$ | $0$ | $0$ | $0$ | $0$ | $0$ | $0$ | $0$ (Net) |
| 10. Rent in Advance | $+1,500$ | $0$ | $0$ | $0$ | $0$ | $0$ | $+1,500$ | $0$ |
| 11. Paid to Ramesh | $-50,000$ | $0$ | $0$ | $0$ | $-50,000$ | $0$ | $0$ | $0$ |
| 12. Received from Suresh | $+15,000$ | $0$ | $0$ | $-15,000$ | $0$ | $0$ | $0$ | $0$ |
| Final Running Totals | ₹1,93,500 | ₹2,75,000 | ₹2,25,000 | ₹15,000 | ₹50,000 | ₹10,000 | ₹1,500 | ₹6,47,000 |
$$\text{Total Assets (₹1,93,500 + ₹2,75,000 + ₹2,25,000 + ₹15,000 = ₹7,08,500)} = \text{Liabilities (₹61,500)} + \text{Capital (₹6,47,000)} = \text{₹7,08,500}$$
🧠⚡ Mind-Blowing Facts to Lock It In Forever
- The Depreciation Secret: Even when no physical cash leaves your pocket, asset wear-and-tear (depreciation) silently chips away at your asset value and owner’s capital. Real businesses account for every invisible loss!
- Advance Receipts Are Not Free Money: Receiving rent or income early feels great, but accounting treats it as an immediate liability because you haven’t earned the right to keep it yet until the service is delivered.
- The Ultimate Dopamine Hit: When you tally up complex inventories, partial supplier payments, debtor collections, and depreciation adjustments, and both sides of the master equation match down to the exact rupee, you realize you have unlocked true financial fluency. You’re practically unstoppable!