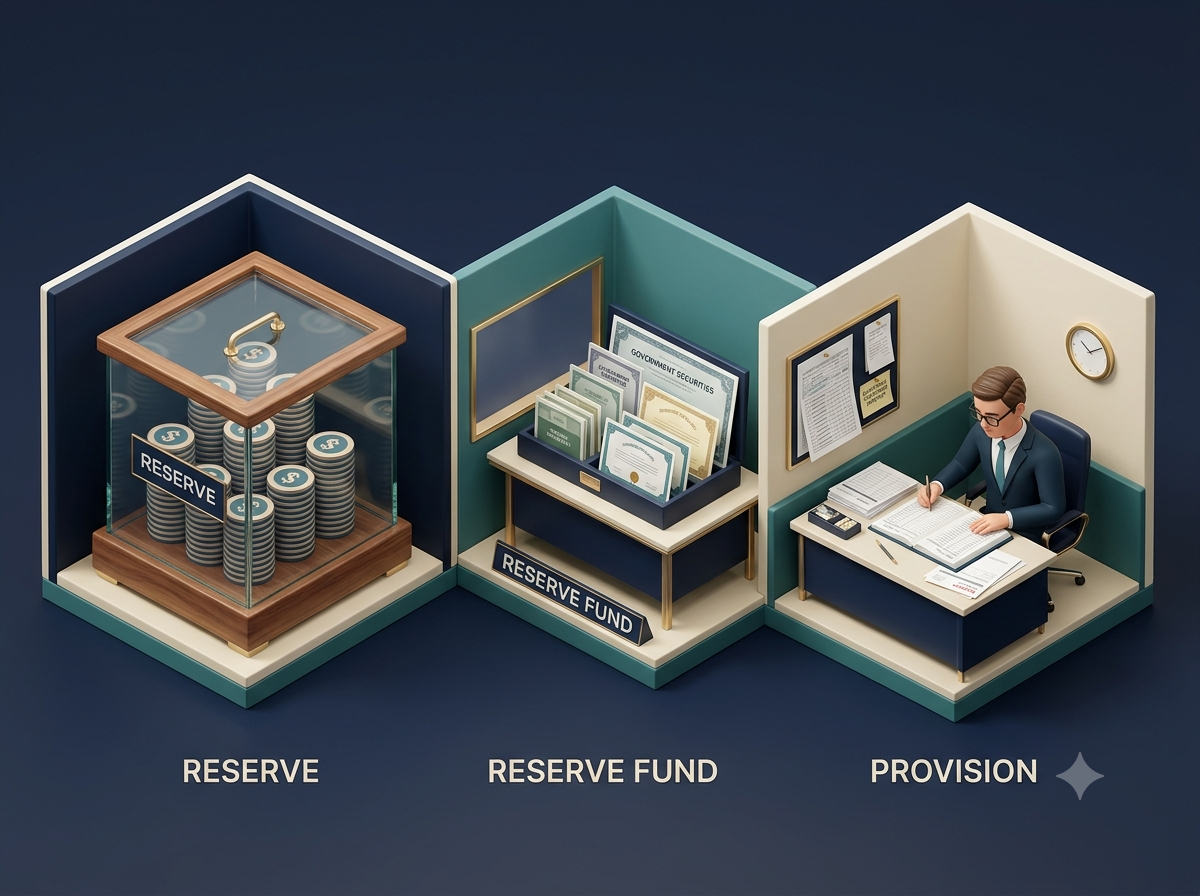
Imagine a business owner preparing for three challenges: an unexpected loss, a future expansion, and a bill that must be accounted for. Can one accounting concept solve all three problems? Not quite! Accountancy has three different concepts for these situations: reserves, reserve funds, and provisions.
1. What Is Meant by a Reserve Fund?
A reserve fund is a fund created by investing a portion of profits in assets outside the business, such as government securities.
For example, a business may invest a portion of its profits in government securities to build a fund for future needs. The investment helps keep that amount separate from the money used for daily operations.
Remember that a reserve does not automatically mean cash kept untouched in a separate bank account. A reserve fund involves investment of the amount set aside.
2. What Is Meant by a Provision?
A provision is an amount charged against profit to meet a known liability or an expected loss or expense whose exact amount may be uncertain.
Suppose a shop sells goods on credit, but some customers may not pay their outstanding debts. The business creates a provision for doubtful debts to account for the expected loss.
Provisions may also be created for taxation and depreciation, according to the applicable accounting treatment.
A provision is an accounting adjustment, not simply money deposited into a separate account.
3. What Is Meant by Reserves?
Reserves are portions of profit retained in the business instead of being distributed to the owners or shareholders.
A business may retain part of its profit to strengthen its financial position, prepare for future difficulties, or support expansion.
For example, a restaurant earns a profit and retains part of it to help finance the opening of another branch. The retained profit contributes to its reserves.
Reserves do not necessarily represent cash sitting separately in a bank account. The funds may be used in the business’s operations.
The Difference to Remember
A reserve retains profit within the business. A reserve fund represents an invested reserve. A provision recognises an expected loss, expense or liability.
Exam-ready memory line: Reserve = profit retained; reserve fund = reserve invested; provision = amount charged against profit for an expected loss, expense or liability.