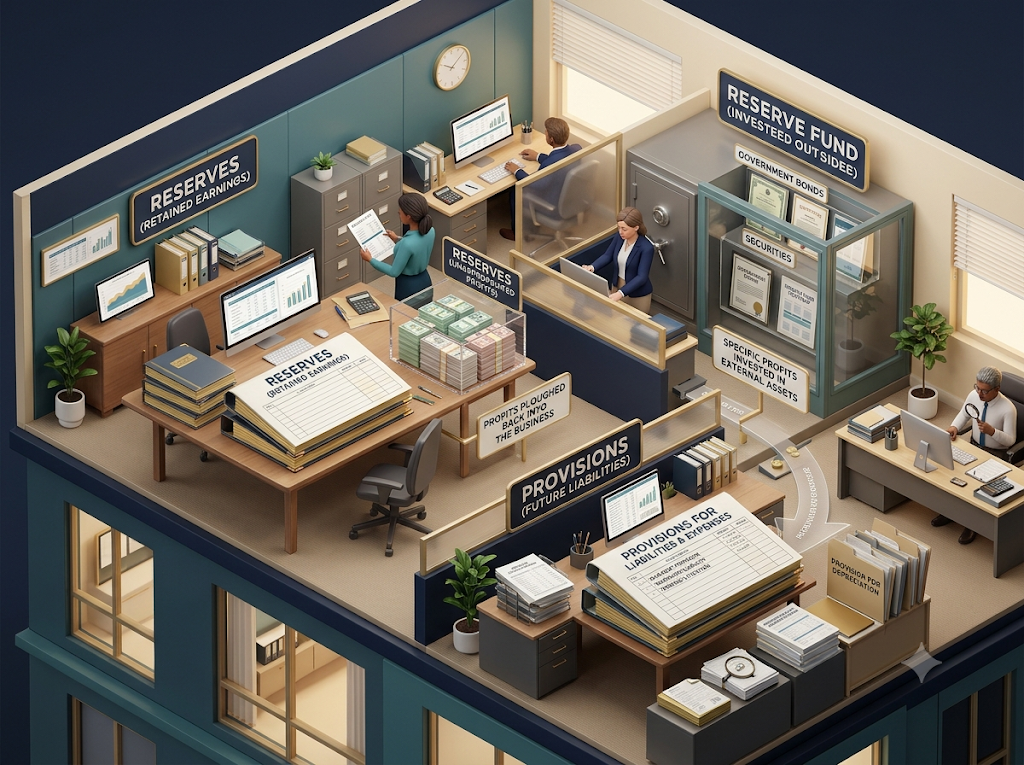
Every business hopes to earn profits, but unexpected expenses, unpaid customer debts, and declining sales can create financial problems. An accountant helps a business recognise expected losses and retain profits for future needs.
Let us explore why provisions and reserves matter.
4. State the Purposes for Which Provisions Are Created
Provisions are created to recognise known liabilities and expected losses or expenses. Their main purposes include:
1. Provision for doubtful debts: This accounts for amounts that customers may fail to pay.
2. Provision for taxation: This recognises an estimated tax liability.
3. Provision for depreciation: This accounts for the decline in the value of a fixed asset over its useful life.
For example, an electronics shop sells goods on credit to several customers. If some customers may not pay their debts, the shop creates a provision for doubtful debts to recognise the expected loss.
Provisions help prevent a business from overstating its profit by ignoring expected expenses or losses.
5. Why Does an Organisation Create Reserves?
Organisations create reserves to strengthen their financial position and prepare for future needs.
The main purposes are:
1. To meet future contingencies: Reserves can help a business face unexpected losses or financial difficulties.
2. To strengthen financial stability: Retaining profits helps build the financial resources of the business.
3. To finance expansion: Reserves may help a business purchase equipment, open new branches, or expand its operations.
4. To support dividend stability: Where permitted, a company may use an appropriate reserve to help maintain dividends during a year of lower profits.
For example, a clothing manufacturer retains part of its profits in a general reserve. If sales decline in a later year, the accumulated reserve may help it manage financial pressure.
However, reserves do not automatically represent separate cash savings, and not every reserve can be used for every purpose.
The Final Distinction
A provision recognises an expected cost, loss or liability. A reserve retains profit to strengthen the business or prepare for future requirements.
Exam-ready answer: Provisions are created to provide for known liabilities and expected losses or expenses, while reserves are created by retaining profits to strengthen the financial position of the business and meet future needs.